Converting 16 Euros to US Dollars: Real Mid-Market Rates vs. Costly Hidden Markups
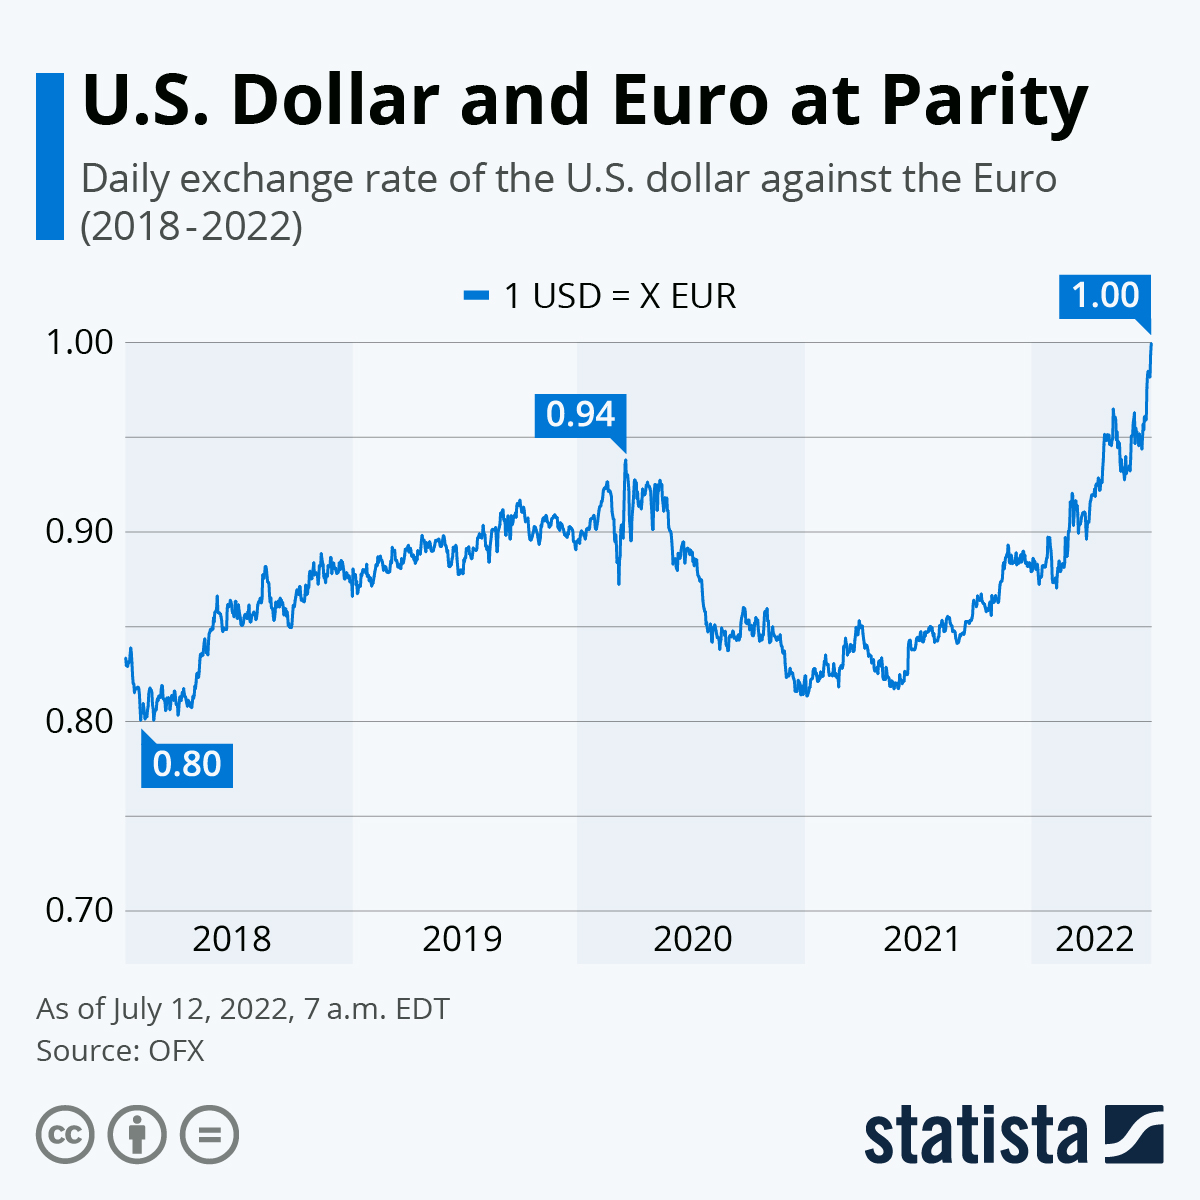
A digital purchase of €16, whether for a niche European software subscription, an overseas train seat reservation, or a boutique import, looks straightforward on screen. Yet American cardholders frequently find their posted bank statements noticeably higher than what standard search engine converters display. According to a recent WSJ Report tracking foreign exchange markets, the euro sank to 16-month lows against the US dollar amid deepening political instability and budgetary gridlock across Paris and Berlin.
That macroeconomic shift recalibrates day-to-day conversion math. With the EUR/USD currency pair trading in the $1.04 to $1.06 corridor, 16 euros represents an unpadded real-time currency valuation of roughly $16.64 to $16.96. The actual debit to your bank account, however, depends far less on institutional trading quotes and far more on retail banking spreads, payment processor margins, and retail dynamic currency tricks.
📌 Key Takeaways:
- The Mid-Market Baseline: At live forex rates, 16 euros converts to approximately $16.64 to $17.10 USD, reflecting recent euro softness tracked by institutions like the European Central Bank.
- The Checkout Spread: Payment gateways and overseas e-commerce stores often levy a 3% to 8% currency conversion spread, pushing that €16 charge to $18.00 or higher.
- Flat Fee Pitfalls: Debit cards featuring flat international payment fees ($1 to $3 per swipe) can instantly inflate a small €16 transaction by an additional 6% to 18%.
Why the Euro Slipped to Multi-Month Lows
Currency fluctuations rarely occur in a vacuum. Recent macro data underscores a diverging fiscal picture between Washington and Brussels. Institutional data from CME Group shows heightened positioning on the euro following political realignments and sovereign debt scrutiny in France. When the European Central Bank adjusts its monetary stance relative to the Federal Reserve, foreign exchange desks reprice wholesale cash instantly.
European debt markets face pressure as national governments grapple with deficit targets, while resilient US productivity metrics have bolstered the greenback. An exchange rate that spent years hovering between $1.08 and $1.12 has narrowed closer toward parity territory. For US buyers shopping from European digital merchants, that shift makes goods nominally cheaper in dollar terms, provided retail intermediaries do not capture the savings before settled funds reach your statement.
The Baseline Math: How Real-Time Forex Rates Price 16 Euros
Every commercial conversion starts with the mid-market rate. Often called the interbank rate, this figure represents the midpoint between institutional "buy" and "sell" quotes on global trading networks. If you consult an online euro to dollar converter or reference official European Central Bank rates, this is the clean, unpadded quote displayed.
For a round sum of €16, the spot math appears clean:
At a live wholesale rate of $1.05 per euro, 16 euros equates precisely to $16.80 USD.
At an alternative rate of $1.07 per euro, 16 euros equals $17.12 USD.
Financial media monitors real-time forex rates to benchmark these small-scale transactions. Yet ordinary consumer accounts almost never execute at pure interbank value. The gap between that raw financial data and the dollar charge on your transaction ledger represents the operational revenue of card networks, settlement rails, and third-party checkout software.
The True Price of 16 Euros Across Common Payment Methods
How you pay determines what 16 euros costs in practice. While financial institutions settle millions of dollars at narrow fraction-of-a-cent margins, consumer retail channels tack on flat administrative fees, percentage markups, or unfavorable retail rates.
| Payment Channel | Effective EUR/USD Rate | Total USD Billed (on €16) | Effective Fee Percentage |
|---|---|---|---|
| Pure Mid-Market Benchmark | $1.050 | $16.80 | 0.0% (Zero padding) |
| No-Foreign-Fee Credit Card | $1.053 | $16.85 | ~0.3% Network margin |
| Standard US Credit Card (3% FX Fee) | $1.082 | $17.31 | 3.0% Bank markup |
| E-Commerce Dynamic Conversion (DCC) | $1.118 | $17.89 | 6.5% Gateway spread |
| Regional Debit Card ($2 Flat Foreign Fee) | $1.175 | $18.80 | 11.9% Effective spread |
Dynamic Currency Conversion: The Checkout Screen Surcharge
When buying an item priced at €16 online, software gateways frequently present a courteous-looking prompt: "Would you like to pay in USD or EUR?"
Selecting USD triggers Dynamic Currency Conversion (DCC). It appears convenient because it displays the exact dollar amount that will hit your statement. What merchant software leaves out is the underlying mechanism. The processor applies an inflated conversion rate, frequently between 4.5% and 7.5% above live market conditions, to cover currency volatility risks and generate ancillary revenue for the payment merchant.
If you confirm payment in US dollars, a €16 bill converted at a wholesale value of $16.80 can easily register at $17.90 to $18.15. Declining DCC and choosing to be billed in the merchant's local currency (€16) forces the transaction to pass down to Visa, Mastercard, or American Express. These core card networks use wholesale exchange rates that sit within fractions of a percent of live interbank trading.
Bank Markup Fees and the Danger of Flat-Rate Spreads
The mathematical impact of foreign transaction fees intensifies significantly on micro-transactions. On a large purchase of €1,600, a standard 3% card fee amounts to $50.40, noticeable, but strictly proportional. On an everyday checkout of €16, fixed fees skew the final equation.
Many traditional credit unions and regional banks levy a dual fee structure: a 1% to 3% cross-border assessment paired with a $1.50 to $3.00 flat international debit fee. Applying a $2.50 flat fee to a €16 invoice (worth roughly $16.80 at baseline) pushes the out-of-pocket cost to $19.30. That represents an effective conversion markup of nearly 15%.
Consumer discussions across personal finance communities consistently highlight this pitfall. Travelers abroad and cross-border online shoppers often check the EUR to USD exchange rate using an automated digital conversion calculator, expect a charge of under seventeen dollars, and feel blindsided when post-clearing banking fees push the line item toward twenty dollars.
Frequently Asked Questions (FAQ)
Q1: What is the current mid-market value of 16 euros in US dollars?
At prevailing forex exchange benchmarks of $1.04 to $1.06 per euro, €16 translates to roughly $16.64 to $16.96 USD before any third-party transaction or processing markups are added.
Q2: Should I select USD or EUR when buying a 16 euro item online?
Always choose to pay in EUR. Paying in USD triggers Dynamic Currency Conversion (DCC), which allows the merchant's payment processor to apply an aggressive retail conversion spread of 4% to 8%. Choosing EUR allows your domestic card issuer to process the currency exchange at competitive wholesale network rates.
Q3: Why did my debit card charge $19 or more for a 16 euro purchase?
Many bank accounts impose flat international processing charges (often $1.50 to $3.00) alongside standard 1% to 3% currency conversion spreads. On small purchases like €16, these combined fixed fees drastically drive up the total cost above the live spot exchange rate.
Managing Micro-Transactions in an Unpredictable Currency Climate
Small foreign purchases reveal the friction embedded within retail cross-border payments. Macroeconomic headwinds, from European sovereign debt questions to shifting central bank interest rate decisions, determine the institutional baseline of the euro against the US dollar. Yet for individuals spending small amounts abroad, payment logistics play a much bigger role in the total price.
To avoid spending $19 or $20 on a €16 charge, use a payment card that waives foreign transaction fees and always process international transactions in the seller's native currency. Understanding the mechanics of retail markups protects your pocketbook from hidden margins, turning global market swings to your advantage rather than the payment processor's balance sheet.
